Save • Give • Grow • Build • Steward
Financial literacy for children begins long before children receive their first paycheck, open their first bank account, or understand terms such as interest, credit, or investment.
Children encounter financial decisions whenever they wait for something they want, choose between two purchases, save birthday money, share with someone else, or decide whether to use a limited resource now or later.
These everyday experiences matter because financial literacy is about more than counting money. The Organization for Economic Co-operation and Development (OECD, 2024) describes financial literacy broadly as financial knowledge and understanding, along with the skills and attitudes needed to apply that knowledge when making financial decisions.
Recent PISA findings reinforce the importance of financial education. For The Now Academy, this raises an important educational question: Why wait until adolescence to begin developing financial habits that children can practice in elementary school? Research suggests starting much earlier is valuable.
Why Financial Literacy for Children Is an Investment in Human Capital
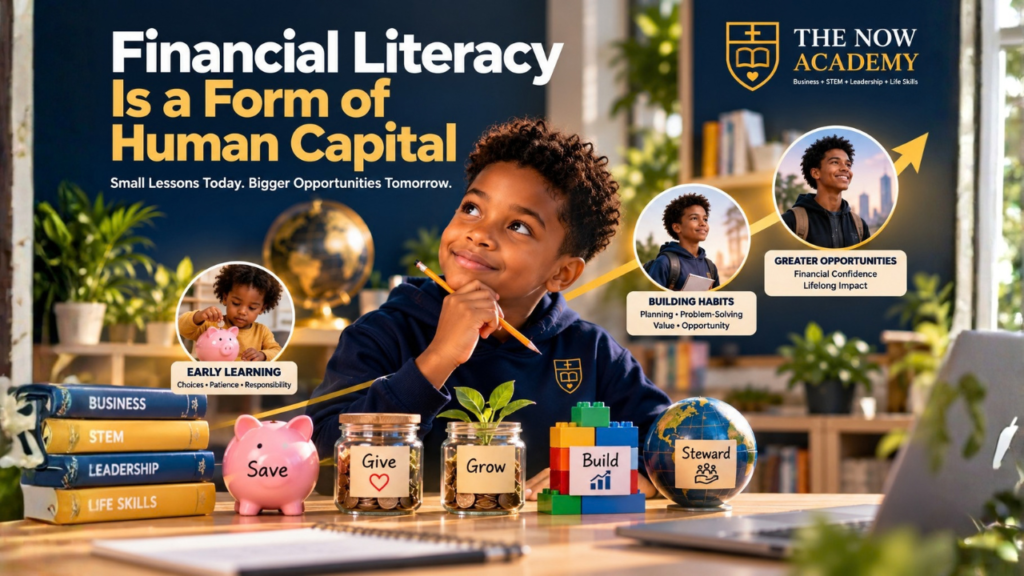
Lusardi and Mitchell (2014) describe financial knowledge as an investment in human capital because it can influence economic decision-making throughout life. Their extensive review links financial literacy to key financial behaviors and outcomes while showing that financial knowledge is unevenly distributed across populations.
Their more recent work continues to argue that financial literacy deserves serious attention as both an educational and economic field (Lusardi & Mitchell, 2023). For children, however, financial education should not begin with complicated lessons about mortgages, retirement accounts, or securities.
It can begin with much simpler concepts: Choices. Consequences. Patience. Resources. Responsibility. Value.
Drever et al. (2015) reviewed research from developmental psychology, consumer science, and related disciplines and concluded that foundations for later financial well-being develop throughout childhood and adolescence.
The researchers particularly highlight executive-function development, financial socialization, and experience-based learning as important components of children’s eventual financial capability.
In practical terms, teaching a five-year-old to wait, plan, choose, and care for resources may look very different from teaching a teenager how to budget. But both can be part of the same developmental journey.
Financial Habits Can Begin Before Children Understand Finance
One reason financial literacy for children should start early is simple: children are already developing resource-related habits. Consider what happens when a child receives $10.
Do they spend it all immediately?
Do they save some?
Do they give some away?
Do they think about what else they could do with it?
Do they understand that choosing one option may mean giving up another?
These are basic financial decisions, even if the child does not yet recognize them as such. Early financial education does not require turning childhood into a finance class. It means recognizing ordinary moments as opportunities to develop patience, judgment, responsibility, and decision-making. A child’s everyday choices can become some of their earliest financial lessons.
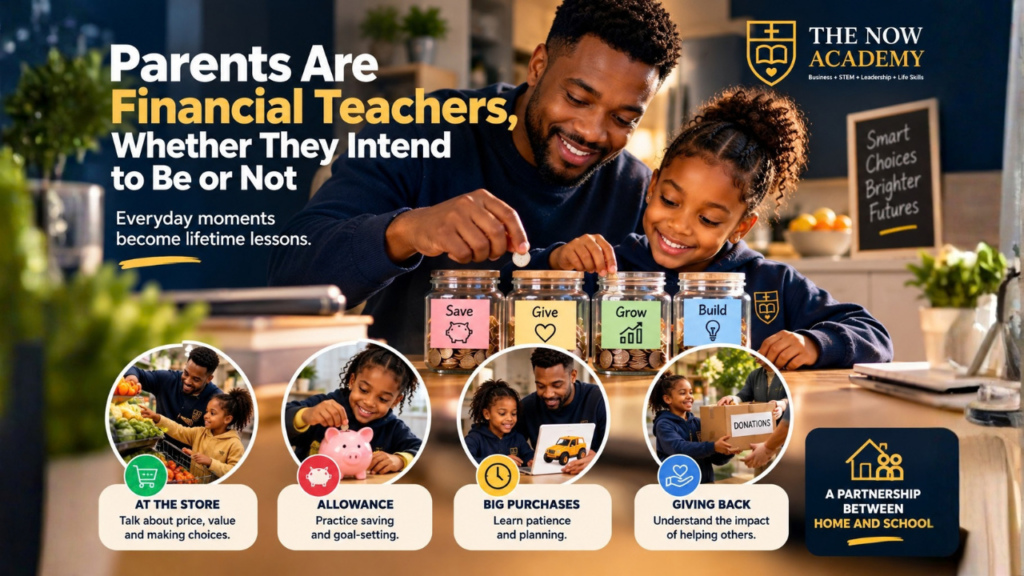
Parents Are Financial Teachers, Whether They Intend to Be or Not
Children learn about money not only through formal instruction but also by observing adults.
Shim et al. (2010) studied 2,098 first-year college students and found that parental financial socialization during adolescence was associated with later financial learning, attitudes, and behaviors. In their analysis, parents played a particularly substantial role relative to work experience and high-school financial education.
Later longitudinal research by Shim et al. (2015) similarly found that parents exerted important influence on changes in young adults’ financial attitudes and behaviors.
Current international evidence points in a similar direction. PISA 2022 data show an association between parent-child discussions about spending decisions and stronger financial-literacy performance among 15-year-olds.
That observational relationship should not be interpreted as proof that the conversations alone caused higher scores. However, the findings reinforce the importance of considering financial literacy as a partnership between home and school.
Parents do not need to be financial experts to participate. A trip to the grocery store can become a conversation about price and value; an allowance can introduce saving and planning; and wanting an expensive toy can become an opportunity to practice patience and goal-setting.
The goal is not to make childhood revolve around money; it is to help children understand how to manage resources responsibly.
Five Financial Literacy Principles Children Can Learn Now
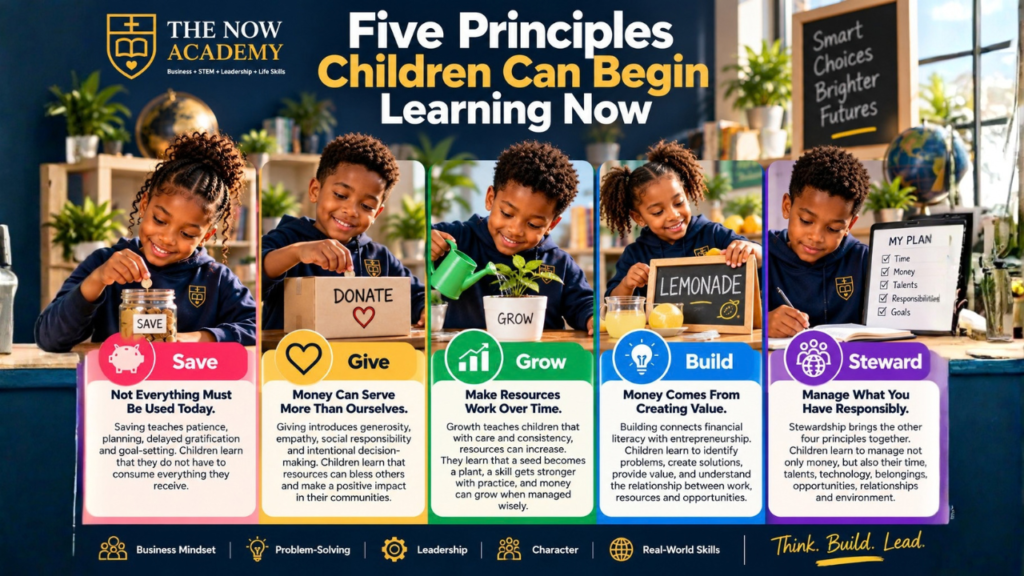
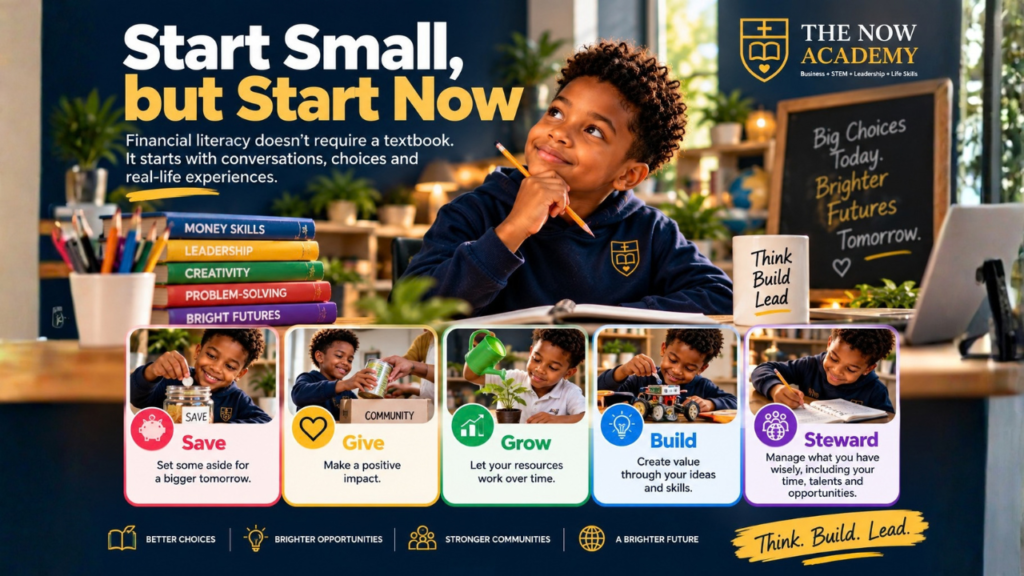
At The Now Academy, financial literacy for children can be translated into five memorable principles:
SAVE • GIVE • GROW • BUILD • STEWARD
Together, these principles connect financial education with entrepreneurship, leadership, decision-making, and character.
Save: Not Everything Must Be Used Today
Saving teaches more than accumulating money; it introduces children to delayed gratification, planning, patience, and goal-setting.
For example, a child who receives $10 can learn that spending the entire amount immediately is only one choice. Another option is setting some aside for something they value more later.
Drever et al. (2015) emphasize the importance of executive-function abilities and experience-based learning in developing financial capability. Saving gives children a practical opportunity to practice planning and self-regulation.
Parents can make saving tangible through transparent jars, envelopes, or age-appropriate digital tools. The lesson is simple: You do not have to consume everything you receive.
Give: Resources Can Serve More Than Ourselves
Financial literacy should not teach children that money’s sole purpose is acquiring more. Giving can introduce generosity, empathy, social responsibility, and intentional decision-making.
Children might choose a cause, help someone in need, contribute to a community project, or use a portion of what they receive to bless someone else.
For a values-centered educational model, this distinction matters. Financial capability without character can become purely transactional. Leadership education invites children to consider a larger question: How can I use what I have to help someone besides myself?
Giving helps children understand that resources can carry responsibility.
Grow: Resources Can Work Over Time
Young children do not need a lesson in portfolio theory to understand growth; start with something familiar. A seed can become a plant with proper care, a skill can become stronger through practice, and money that is saved and eventually invested can also grow over time.
As children mature, this foundation can expand into concepts such as compound interest, investing, risk, diversification, and long-term planning. Lusardi and Mitchell (2014, 2023) demonstrate why financial knowledge matters for decision-making throughout adulthood.
Beginning with developmentally appropriate concepts can prepare children for increasingly sophisticated financial decisions later.
Build: Money Can Come From Creating Value
This principle connects financial literacy for children directly with entrepreneurship. Instead of only asking children: “What do you want to buy?” Parents and educators can also ask: “What could you create?”
A child might make bracelets, organize a small lemonade stand with parental supervision, design greeting cards, solve a household problem, or develop a classroom business project. The objective is not to turn children into miniature executives; it is to help them understand the relationship among:
Problems → Solutions → Work → Value → Resources
This is where Business + STEM education becomes especially powerful. Students can identify a problem, design a solution, calculate material costs, create a prototype, communicate its value, test their thinking, and reflect on what they learned. Financial literacy becomes something children do, not merely something they memorize.
Research supports the broader value of structured financial education. Kaiser and Menkhoff’s (2020) meta-analysis of 37 experimental and quasi-experimental school-based studies found meaningful average improvements in financial knowledge and smaller positive effects on financial behaviors.
Steward: Manage What You Have Responsibly
Stewardship brings the other four principles together. A steward learns to ask:
What do I have?
What should I do with it?
What happens if I waste it?
How can I use it wisely?
Stewardship also extends beyond money; children can learn to steward their:
Time. Talents. Technology. Belongings. Opportunities. Relationships. Environment.
That makes financial literacy part of leadership development, not simply another mathematics lesson.
Financial Literacy for Children Must Move From Knowing to Doing
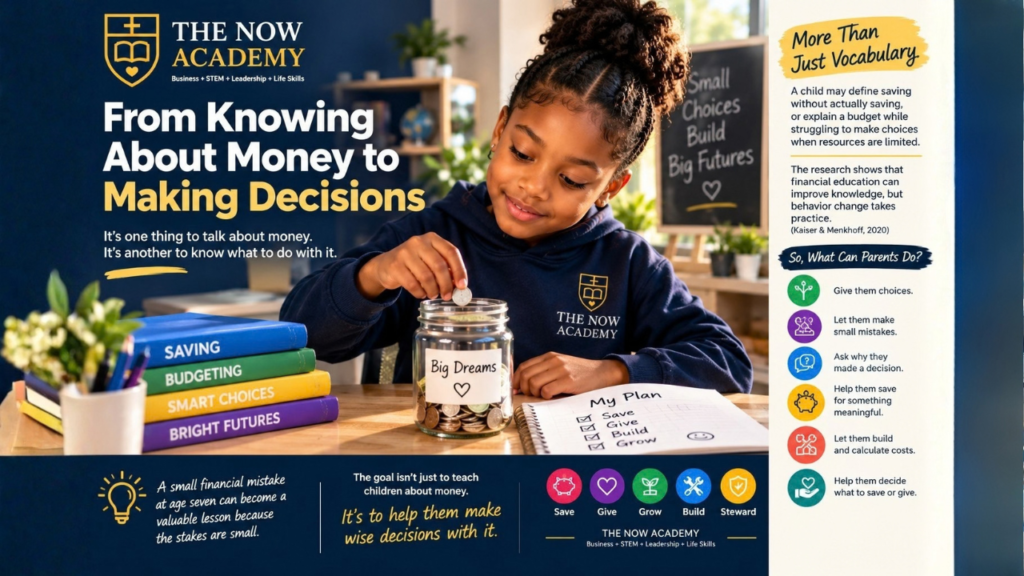
Effective financial education should go beyond vocabulary. A student might be able to define saving without actually saving; a child might explain what a budget is while still struggling to make decisions when resources are limited.
That distinction between knowledge and application is central to The Now Academy’s educational philosophy. Research also suggests that financial education can improve knowledge while effects on actual behavior tend to be more modest. Kaiser and Menkhoff’s (2020) findings remind us of an important principle:
Knowing is not the same as doing. Children therefore need opportunities to practice. Give them choices, allow them to make small mistakes, ask why they made a particular decision, let them save toward something meaningful, give them opportunities to create something and calculate what it costs, and help them consider what portion of their resources they might save, give, grow, build with, or steward.
A small financial mistake at age seven can become a valuable learning experience precisely because the stakes are small.
Why Should Financial Literacy for Children Start Early?
Financial literacy for children should start early because children begin making decisions involving resources, choices, patience, saving, sharing, and value long before adulthood. Age-appropriate financial education can give children opportunities to practice decision-making and develop habits that become increasingly important as their financial responsibilities grow.
Early financial literacy does not require teaching young children complicated investment strategies; it can begin with practical experiences involving:
Saving. Giving. Spending. Planning. Comparing choices. Creating value. Managing resources.
The lesson can grow in complexity as the child grows.
The Role of Schools: Connect Money to Real Life
Schools can make financial education more practical; imagine a student identifying a problem and designing a simple product to solve it. Now ask:
What materials are needed?
How much do those materials cost?
Who would use the product?
What makes it valuable?
What price might someone reasonably pay?
How could the student improve the design?
Should some of the proceeds be saved?
Could some be given?
What resources would be needed to build the next version?
Suddenly, mathematics, entrepreneurship, STEM, communication, leadership, and financial literacy are interacting in one learning experience. That kind of connection between classroom learning and real-world application can make education more meaningful.
Financial Literacy for Children Is Preparation for Life
Financial literacy for children is not simply about teaching students how to count dollars and cents; it is about helping them understand:
Choices. Consequences. Value. Responsibility. Opportunity. Stewardship.
A child who learns to save is practicing patience.
A child who compares alternatives is practicing decision-making.
A child who creates something valuable is beginning to understand entrepreneurship.
A child who manages limited resources is practicing responsibility.
These lessons can begin long before adulthood. At The Now Academy, financial literacy is part of a broader vision for helping children become thinkers, builders, problem-solvers, and leaders.
Through Business + STEM education and real-world learning experiences, students can begin connecting classroom learning with decisions they will eventually make in life.
We do not simply want children to know what money is. We want them to learn how to think about resources, make responsible choices, create value through their abilities, and use what they have with wisdom and purpose.
Because long before children manage a paycheck, they are already learning how to manage choices.
SAVE. GIVE. GROW. BUILD. STEWARD.
THINK. BUILD. LEAD.
THE NOW ACADEMY
Empowering Future Leaders Through Business + STEM
References
Drever, A. I., Odders-White, E., Kalish, C. W., Else-Quest, N. M., Hoagland, E. M., & Nelms, E. N. (2015). Foundations of financial well-being: Insights into the role of executive function, financial socialization, and experience-based learning in childhood and youth. Journal of Consumer Affairs, 49(1), 13–38. https://doi.org/10.1111/joca.12068
Kaiser, T., & Menkhoff, L. (2020). Financial education in schools: A meta-analysis of experimental studies. Economics of Education Review, 78, 101930. https://doi.org/10.1016/j.econedurev.2019.101930
Lusardi, A., & Mitchell, O. S. (2014). The economic importance of financial literacy: Theory and evidence. Journal of Economic Literature, 52(1), 5–44. https://doi.org/10.1257/jel.52.1.5
Lusardi, A., & Mitchell, O. S. (2023). The importance of financial literacy: Opening a new field. Journal of Economic Perspectives, 37(4), 137–154. https://doi.org/10.1257/jep.37.4.137
Organization for Economic Co-operation and Development. (2024). PISA 2022 results (Volume IV): How financially smart are students? OECD Publishing. https://doi.org/10.1787/5a849c2a-en
Shim, S., Barber, B. L., Card, N. A., Xiao, J. J., & Serido, J. (2010). Financial socialization of first-year college students: The roles of parents, work, and education. Journal of Youth and Adolescence, 39(12), 1457–1470. https://doi.org/10.1007/s10964-009-9432-x
Shim, S., Serido, J., Tang, C., & Card, N. (2015). Socialization processes and pathways to healthy financial development for emerging young adults. Journal of Applied Developmental Psychology, 38, 29–38. https://doi.org/10.1016/j.appdev.2015.01.002